
Guide
Working with your insurance after storm damage
After a hail or wind storm, many homeowners are dealing with an insurance claim for the first time. The process is easier when you know the steps and keep good records. This guide covers what usually happens, from the day of the storm to the finished repair. It is general information: your policy and your insurance company decide what is covered.
Right after the storm
Start with safety, and stay off the roof. Then record what happened while it is fresh: the date and time of the storm, and photos and video of the damage you can see from the ground and inside the house. Our guide to signs of hail and wind damage lists what to look for.
If water is getting in, take reasonable steps to prevent more damage: catch drips, move belongings, cover a broken window. Most policies expect homeowners to protect the property from further damage. Keep receipts for anything you buy, since they may be part of the claim.
Read your policy and contact your insurer
Before you call, find your policy and look for the parts that cover wind and hail, your deductible, and any time limit for reporting damage. Some policies have a separate deductible for wind and hail. If anything is unclear, your agent or insurance company can explain it.
Then contact your insurer to report the damage and start a claim. Write down your claim number, the name of everyone you talk to and what they tell you. Keeping one folder, paper or digital, for the whole claim makes every later step easier.
Get a professional inspection
A roofing contractor can inspect the roof up close and document damage you cannot see from the ground. Omega Exteriors offers a free roof inspection that includes looking for storm damage, and its storm restoration work begins with a detailed inspection to identify the damaged areas. Knowing what the damage looks like before the adjuster arrives helps you ask the right questions.
Be careful with anyone who knocks on your door right after a storm and pushes you to sign that day. Take time to check out any company, read anything before you sign it, and make sure you understand what you are agreeing to.
The adjuster's visit
Your insurance company will usually send an adjuster to inspect the damage. The adjuster looks at the roof, siding, gutters, windows and anything else you reported, and writes up what the insurer will consider. It helps to have your photos ready and to point out everything you noticed, including damage inside the house.
Many homeowners ask their contractor to be there for the adjuster's inspection so both are looking at the same damage. In reviews on Omega Exteriors' reviews page, several homeowners describe an Omega project manager meeting the adjuster and helping with the claim paperwork. If you would like that, ask when you call.
Reading the estimate
After the inspection, the insurer sends an estimate or a statement of what it will pay for. Read it line by line and compare it with what you and your contractor found. Check that every damaged area is listed: each slope of the roof, the gutters, the siding on each side of the house, window screens and wraps, and any interior damage.
If something is missing or you disagree with the scope, ask your insurer how to request a review. Ask, too, how and when payments are made, and whether your mortgage company needs to be included on the check. Your deductible is the part you pay, as set out in your policy.
Getting the work done
Once the claim is approved, choose your materials and schedule the work. Keep the claim number handy, and keep copies of the contract, any change orders and the final invoice, since your insurer may ask for them. When the work is done, do a final walkthrough and file the paperwork with your home records.
Omega Exteriors provides roof storm damage restoration, siding storm damage restoration, gutter storm damage restoration and window storm damage restoration. The storm damage guide shows what it does for each trade. To schedule an inspection, call (651) 998-8500 or request a free estimate.
Services
Services and products in this guide
4 pages this guide links to.
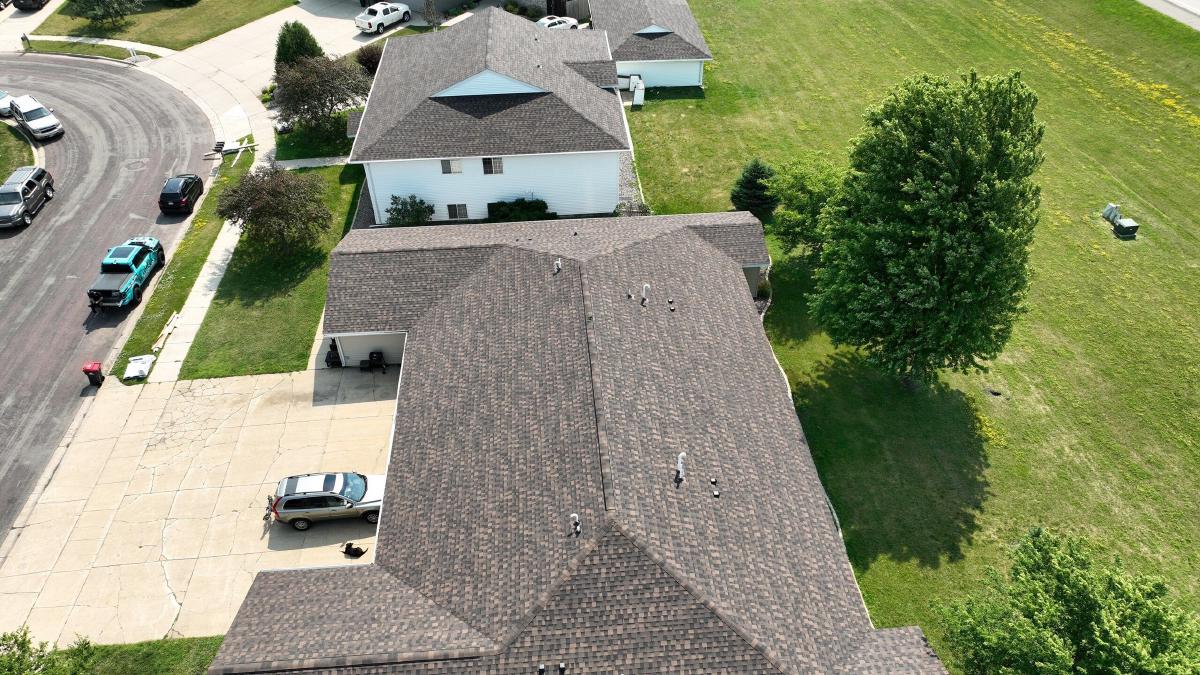
Roof Storm Damage Restoration
Our roof storm damage restoration provides rapid, thorough repairs, using advanced techniques to restore integrity.
Learn more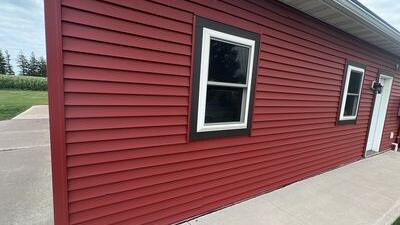
Siding Storm Damage Restoration
Our siding storm damage restoration swiftly repairs and strengthens your home, utilizing expert assessments and superior materials.
Learn more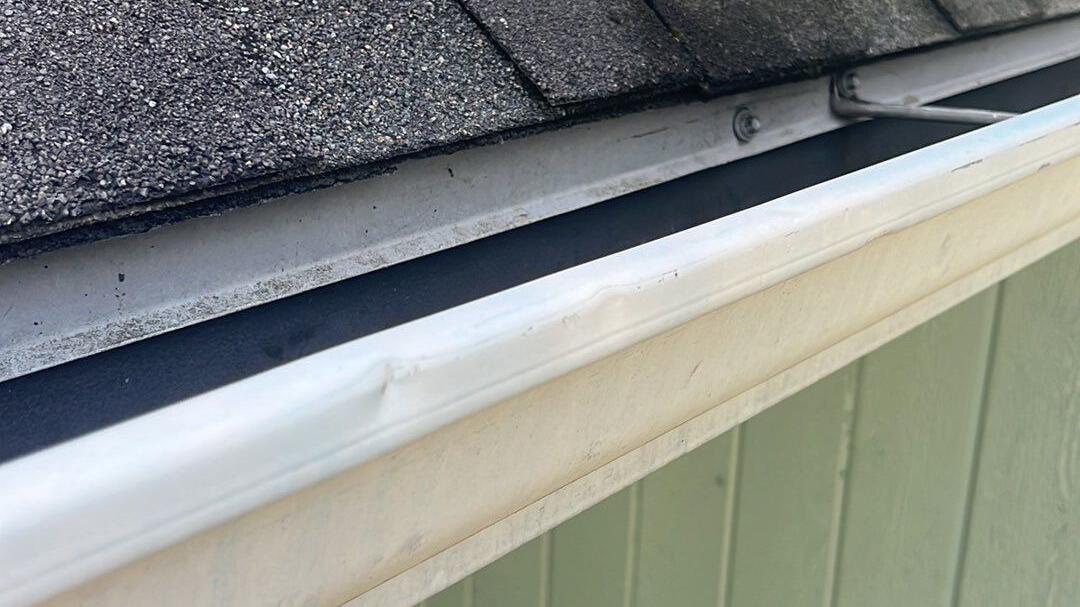
Gutter Storm Damage Restoration
Our gutter storm damage restoration service ensures swift, reliable repairs to protect your home from future issues.
Learn more
Window Storm Damage Restoration
Our window storm damage restoration swiftly restores your home's security and beauty.
Learn more
Guides
Helpful guides
3 guides from Omega Exteriors.
Roof repair or roof replacement: how to decide
How to tell whether your roof needs a repair or a full replacement: its age, the damage, leaks, the roof deck and your plans.
Learn more
Signs of hail and wind damage on your roof, and what to do first
What hail and wind damage looks like on shingles, gutters, siding and windows, and the first steps to take after a storm.
Learn more
Storm damage restoration
Learn more
FAQ
Frequently asked questions
4 questions and answers.
Should I call my insurance company or a contractor first?
Either order can work. Many homeowners have a contractor inspect the roof first so they know what damage there is, then contact their insurer. Check your policy for any time limit on reporting damage, and do not wait long.
Does insurance cover a new roof after hail?
It depends on your policy, the damage the adjuster finds and your deductible. Your insurance company decides what is covered, so read your policy and ask your agent if anything is unclear.
Can my contractor be there when the adjuster comes?
Yes, many homeowners ask their contractor to attend. It helps make sure everyone looks at the same damage. Ask your insurer when the adjuster will visit and share the time with your contractor.
What should I keep for my claim?
Keep photos and video of the damage, the date of the storm, your claim number, notes from every call, receipts for temporary repairs, the insurer's estimate, and your contractor's contract and final invoice.
Ready when you are
Tell us what you need and we will get back to you — Monday–Friday 7:00 AM–7:00 PM.
Request a free estimate
Tell us about your project
Send a few details and Omega Exteriors will reply by phone or email.